
Uber / Delivery Hero: a EUR 10 billion question
Uber offered EUR 33 a share for Delivery Hero and the board said no. The deal is strategically compelling; the price is not. Our fair value: EUR 36 to 38 a share.
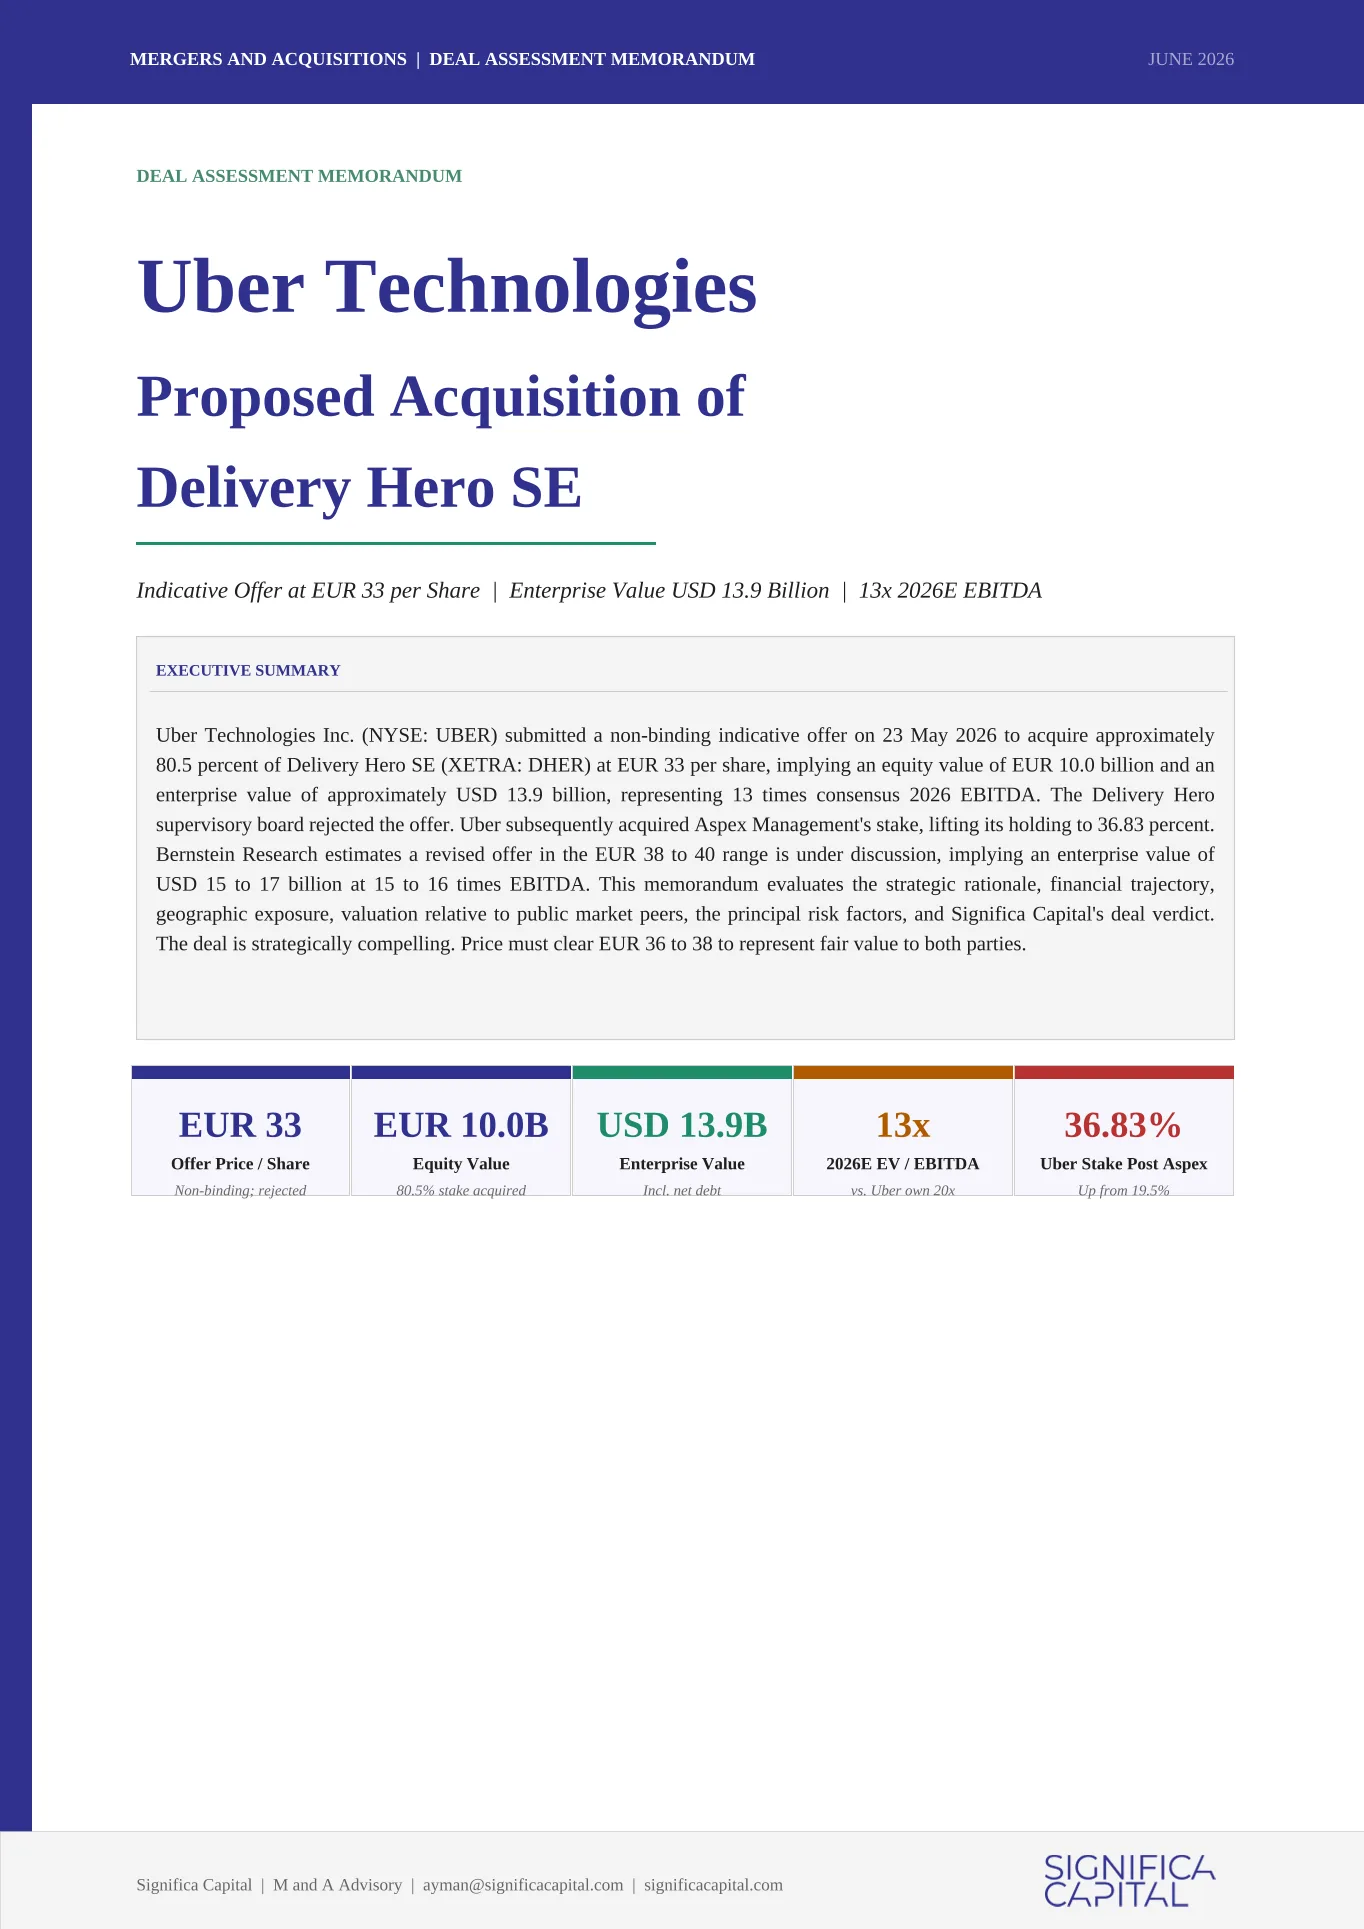
On 23 May 2026, Uber Technologies submitted a non-binding indicative offer to acquire Delivery Hero SE at EUR 33 per share, implying an enterprise value of USD 13.9 billion and a multiple of 13x consensus 2026 EBITDA. The board rejected it. Uber then acquired Aspex Management's stake, lifting its position to 36.83 percent.
This is one of the more strategically loaded deals in global food delivery right now.
Why Uber wants this
DoorDash acquired Deliveroo in 2025. Uber cannot afford to let a second major international asset fall to its primary rival. Delivery Hero brings approximately EUR 57 billion in gross order value across 65 countries, talabat and Hungerstation in the GCC where Uber Eats has zero meaningful presence, a quick commerce platform doing EUR 7.5 billion in GMV, and two consecutive years of positive free cash flow after years of deep losses.
Uber is not buying a broken company. It is buying a turning one, at a 35 percent discount to its own trading multiple.
Why the board said no
EUR 33 does not reflect fair value. Naspers holds 26 percent and has signalled a minimum price meaningfully above EUR 40. At EUR 40, the enterprise value approaches USD 17 billion at 16x EBITDA. Every EUR 1 increase in the offer price adds approximately EUR 300 million to the cost. Regulatory exposure across Europe is material, with Spain, Turkey, Portugal, Sweden and Norway all representing direct overlap with Uber Eats. A 12 to 18 month EC review is the base case, and required divestitures could strip EUR 5 to 10 billion of gross order value from the combined entity.
Our verdict
The deal is strategically compelling. The price is not. Significa Capital's fair value sits at EUR 36 to 38 per share, implying an enterprise value of USD 15 to 16 billion at 14 to 15x 2026E EBITDA. That is the zone where the deal works for Uber's shareholders without overpaying, and where Delivery Hero's board can credibly recommend acceptance.
The watch list: does Uber raise to EUR 36 to 40 in a binding offer, does DoorDash make a move, and how does Naspers vote.
Get the full report
Abstract
Uber offered EUR 33 a share for Delivery Hero and the board said no. The deal is strategically compelling; the price is not. Our fair value: EUR 36 to 38 a share.
Tell us who you are and we will email you a download link. It works for 7 days.
Check your inbox
We have sent a download link to the address you gave. It works for 7 days. If it has not arrived in a few minutes, check your spam folder.
Published in
For institutional and professional investors. Not investment advice.