
European equities: pricing the left tail
We ran 60,000 Monte Carlo simulations on the EURO STOXX 50 to stress-test the 12-month risk/reward distribution. The median masks substantial left-tail exposure.

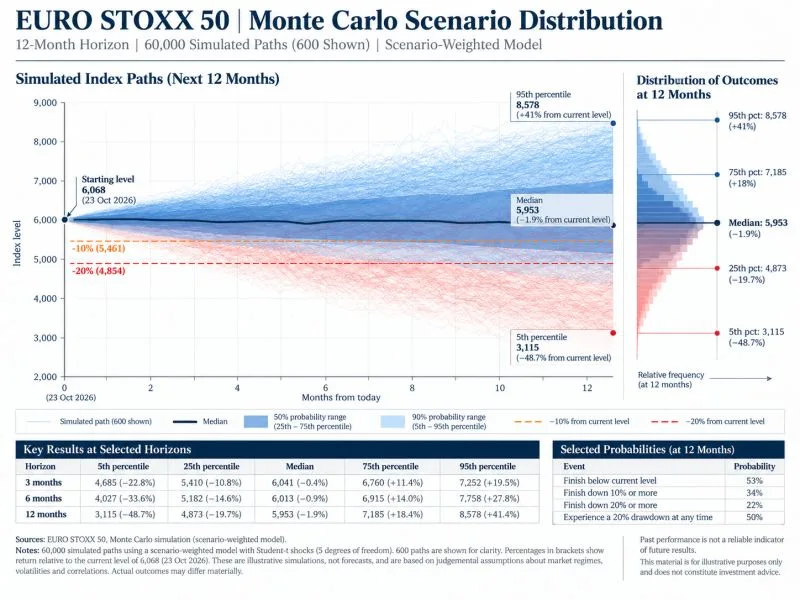
We ran 60,000 Monte Carlo simulations on the EURO STOXX 50 to stress-test the 12-month risk/reward distribution.
The readout:
- Median return: −1.9%
- Probability of a 10%+ correction at year-end: 34%
- Probability of a 20%+ intrayear drawdown: 50%
The median masks substantial left-tail exposure.
The key question is whether the current repricing remains a multiple-compression trade or evolves into an earnings downgrade cycle, amplified by sovereign spreads, energy shocks, and tighter credit conditions.
For allocators, this is less about calling the bottom and more about managing drawdown convexity, preserving dry powder, and optimizing entry points.
Scenario-weighted, assumption-driven probabilities; not statistically calibrated forecasts.
Published in
Eighteen years in investment management, M&A and financial technology. A CFA Charterholder, he leads investment analysis, valuation and fund structuring across Significa's advisory and investment practices, and teaches valuation and fund structures in the CVC Builder curriculum. Concurrently Chief M&A and Growth Officer at AlternativeSoft in London; co-founder of MarkeScope, which developed the first stock-screening solution to incorporate risk measures. Treasurer of CFA Society Egypt; BSc Electrical, Electronics and Communications Engineering, Cairo University.