
Tech M&A is getting harder
Tech M&A is getting harder. And I think most people are underestimating how much.

Tech M&A is getting harder. And I think most people are underestimating how much.
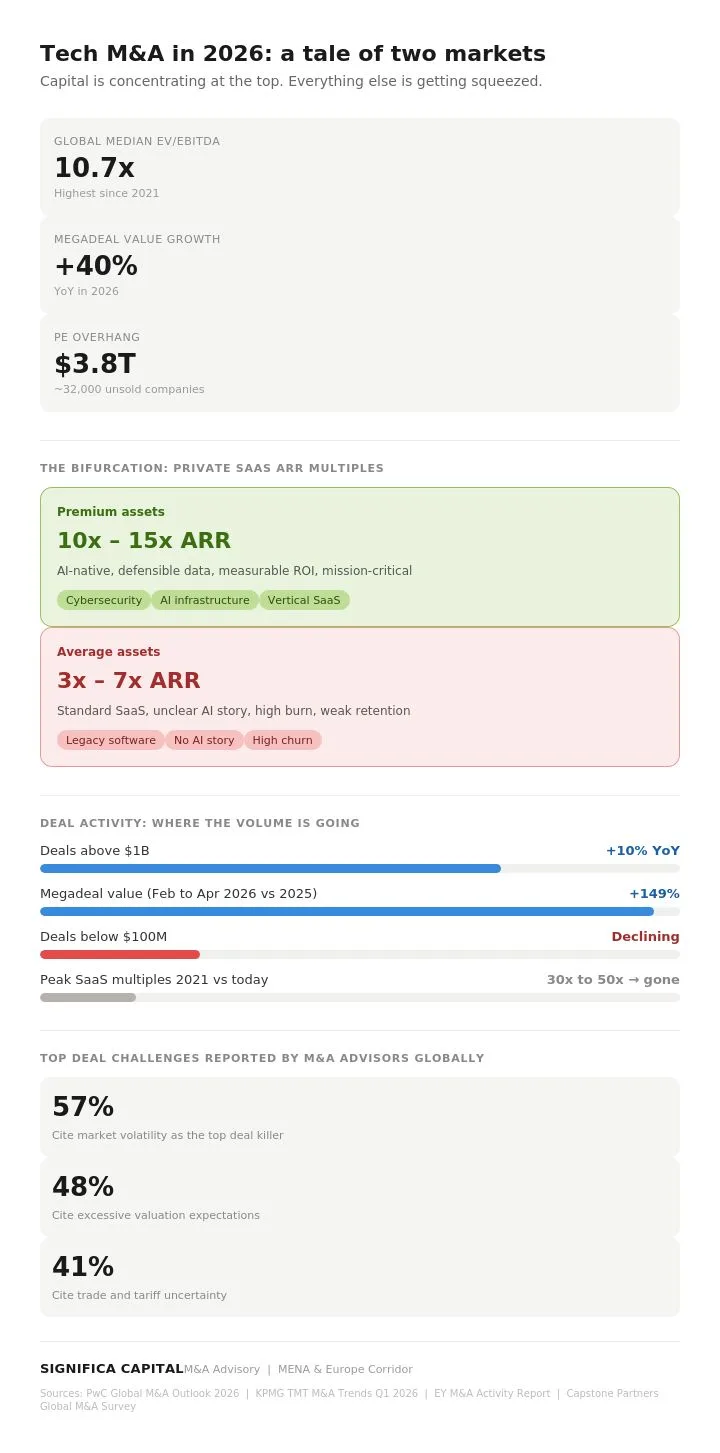
The headline numbers look great. Global median EV/EBITDA just hit 10.7x, the highest since 2021 (we call it the castle in the skies year). Megadeal value is on track to rise 40% in 2026. If you read the top line, you would think we are in a boom and that Christmas is coming early this year.
But that is not what I am seeing on the ground.
What is actually happening is a brutal bifurcation (super technical term for market diverging into two directions).
In layman terms, capital is concentrating at the very top of the market while becoming increasingly selective everywhere else. Deals above $1B are up 10% this year. Deals below $100M are declining. The middle is getting squeezed.
For mid-market tech sellers, this is a difficult environment to navigate.
The multiple spread says it all. Private SaaS in the lower middle market is clearing 3x to 7x ARR today. AI-native infrastructure and cybersecurity businesses are commanding two to three times that. Legacy software, where AI is threatening to replicate core functionality at a fraction of the cost, is getting repriced with no clear floor. In other words, a free fall!
I have never seen the gap between a top-tier asset and an average one this wide.
What makes it harder is that sellers are still anchoring to 2021 peak comps, SaaS at 30x to 50x revenue, when the market has completely moved on. Nearly half of M&A advisors globally now cite excessive valuation expectations as the top operational challenge. That gap between expectation and reality is where deals die.
What adds some gas to the fire is that roughly 32,000 unsold sponsor-backed companies worth $3.8 trillion sitting in PE portfolios, and you have a supply dynamic that is not going away quietly.
My view is simple. In this market, positioning matters more than timing. The quality of your story and your process determines your outcome far more than the macro backdrop.
Happy to discuss if you are thinking through a tech transaction in the MENA or Europe corridor.
Published in
Eighteen years in investment management, M&A and financial technology. A CFA Charterholder, he leads investment analysis, valuation and fund structuring across Significa's advisory and investment practices, and teaches valuation and fund structures in the CVC Builder curriculum. Concurrently Chief M&A and Growth Officer at AlternativeSoft in London; co-founder of MarkeScope, which developed the first stock-screening solution to incorporate risk measures. Treasurer of CFA Society Egypt; BSc Electrical, Electronics and Communications Engineering, Cairo University.