
There are two sides to every private credit deal
There are two sides to every private credit deal, and most content only speaks to one of them: dilution for the borrower, origination for the lender.
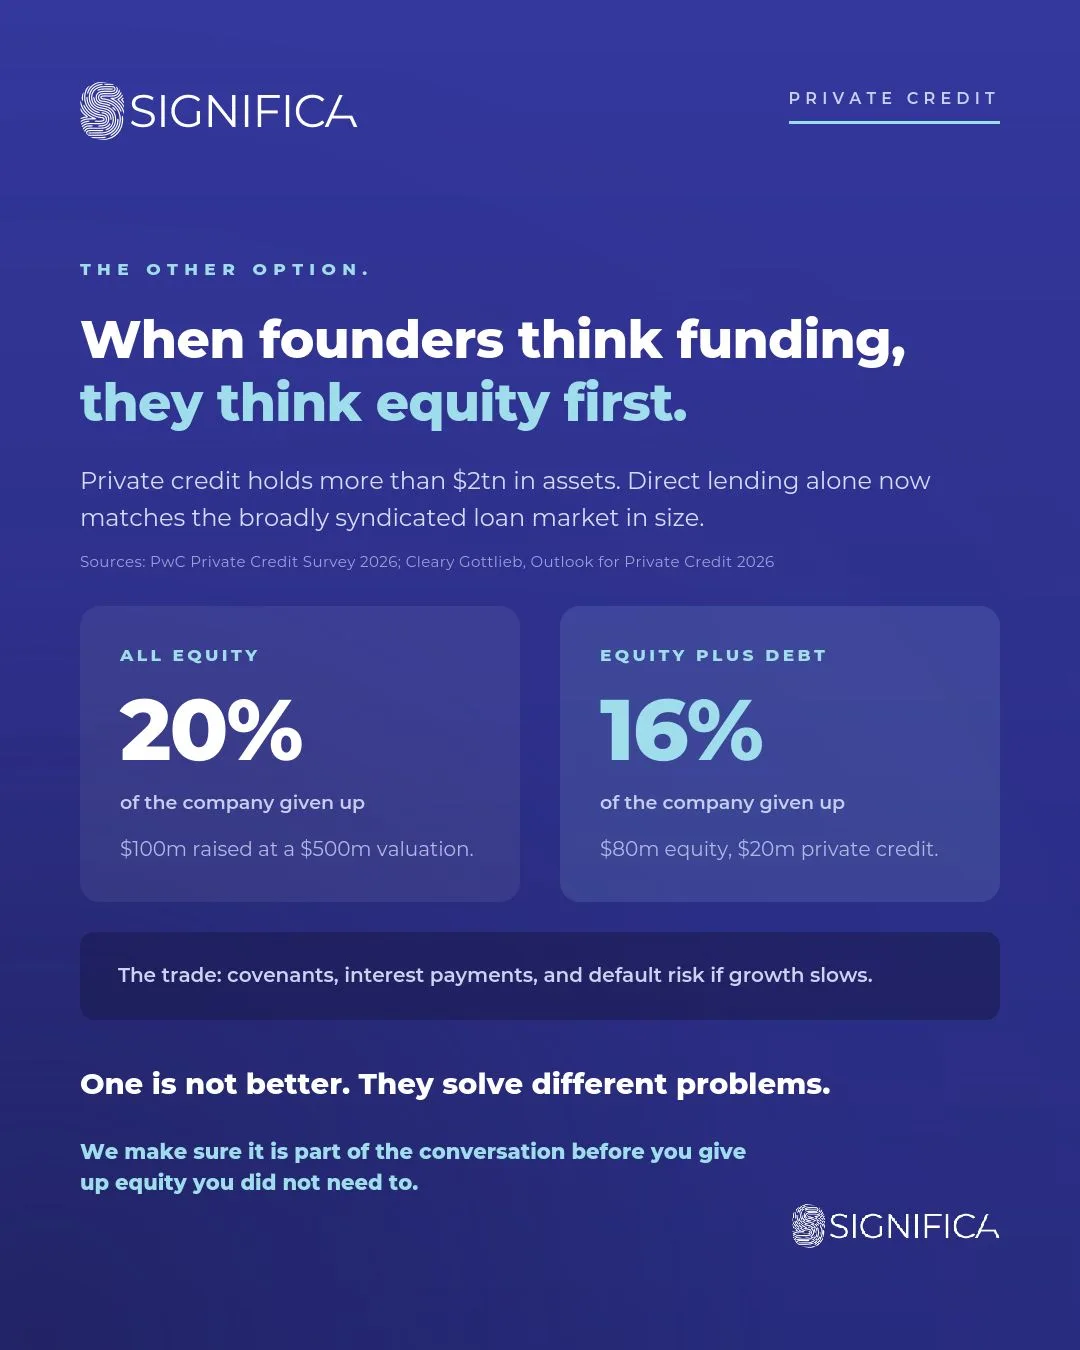
There are two sides to every private credit deal, and most content only speaks to one of them.
On the borrower side, the question is dilution. J.P. Morgan puts it in numbers: a founder raising $100m entirely in equity at a $500m valuation gives up 20% of the company. Raise $80m in equity and $20m in credit, and it becomes 16%. Four points of ownership, worth $20m on that valuation, staying where it started.
On the lender side, the question is origination. Private credit has grown past $2tn in assets, with direct lending now matching the broadly syndicated loan market in size, and the constraint is no longer capital. It is finding well-structured deals with borrowers who understand what they are signing.
That gap is the work. A borrower who has been walked through covenants, interest and downside scenarios before the term sheet arrives is a better counterparty for everyone at the table.
Significa Capital sits between the two, structuring debt for growth companies across Europe and MENA and matching them with lenders whose mandates actually fit.
If you are deploying credit or considering raising it, this is where we publish how we think.