
Screening the vertical AI space: Butterfly Network
Been spending time lately screening the vertical AI space on the public markets side. Looking for companies where the moat is structural, not narrative.

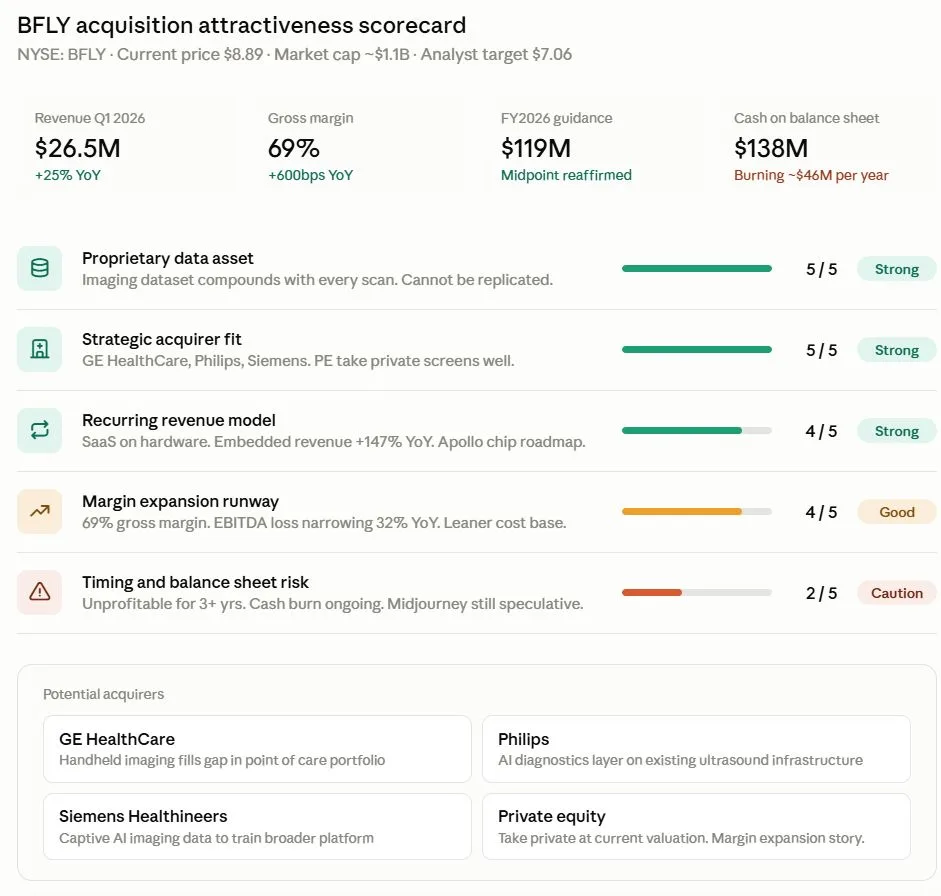
Been spending time lately screening the vertical AI space on the public markets side. Looking for companies where the moat is structural, not narrative.
BFLY came up.
Butterfly Network. Handheld AI ultrasound. Replaces a $30,000 hospital machine with a $400 device that plugs into a smartphone. The unit economics sound wrong until you understand what sits underneath.
Proprietary imaging dataset that compounds with every clinical scan. FDA clearance that takes years to replicate. Workflow embedded deep enough in clinical settings that switching carries real retraining and revalidation costs. Three layers of defensibility that reinforce each other.
On the financials. Q4 2025 revenue up 41%. Q1 2026 up 25%. Gross margin at 69%. Full year guidance of $117 to $121M reaffirmed.
Still loss making. Probably for another three years. Cash burn is real and the Midjourney partnership, while strategically interesting, dropped the stock 18.8% in a single session when the market remembered that a partnership announcement is not a revenue line.
Stock at $8.89. Analyst consensus target at $7.06.
Now the M&A angle, which is where it gets interesting.
The installed base creates a captive data asset that no acquirer can replicate organically. The embedded revenue model, software subscriptions layered on top of the device, is exactly the recurring revenue profile that strategic buyers pay a premium for. The Apollo chip roadmap and the Butterfly Embedded platform position this as infrastructure, not just a medical device.
Obvious strategic fit with GE HealthCare, Philips, Siemens Healthineers, or any large medtech looking to close the gap on AI native imaging. A private equity take private at current valuations also screens attractively given the margin expansion runway.
The risk is timing. Deep negative margins and ongoing cash consumption mean the acquirer needs conviction on the adoption curve before the balance sheet becomes a problem.
Worth watching closely.
This is not a buy or sell recommendation. Purely a market thought shared with peers for discussion.
Published in
Eighteen years in investment management, M&A and financial technology. A CFA Charterholder, he leads investment analysis, valuation and fund structuring across Significa's advisory and investment practices, and teaches valuation and fund structures in the CVC Builder curriculum. Concurrently Chief M&A and Growth Officer at AlternativeSoft in London; co-founder of MarkeScope, which developed the first stock-screening solution to incorporate risk measures. Treasurer of CFA Society Egypt; BSc Electrical, Electronics and Communications Engineering, Cairo University.